The housing market isn't moving as one unified market anymore. Instead, it's being shaped by four distinct groups: cash buyers, buyers using financing, homeowners who feel tied to their current low mortgage rate, and builders with new homes to sell. Which group you fall into can make a big difference in how you approach buying or selling.
Ryan Serhant, CEO of SERHANT, puts it this way:
“There is no longer a housing market . . . There are four Americas.”
Let's take a closer look at each group and what it could mean for you.
Cash Buyers: 1 in 4 Buyers Are Paying with Cash
If you already own a home, the equity you've built could give you the option to purchase your next home with cash. According to the National Association of Realtors (NAR), all-cash purchases accounted for 26% of existing home sales this summer. That's about 1 in every 4 buyers completing a purchase without taking out a mortgage.
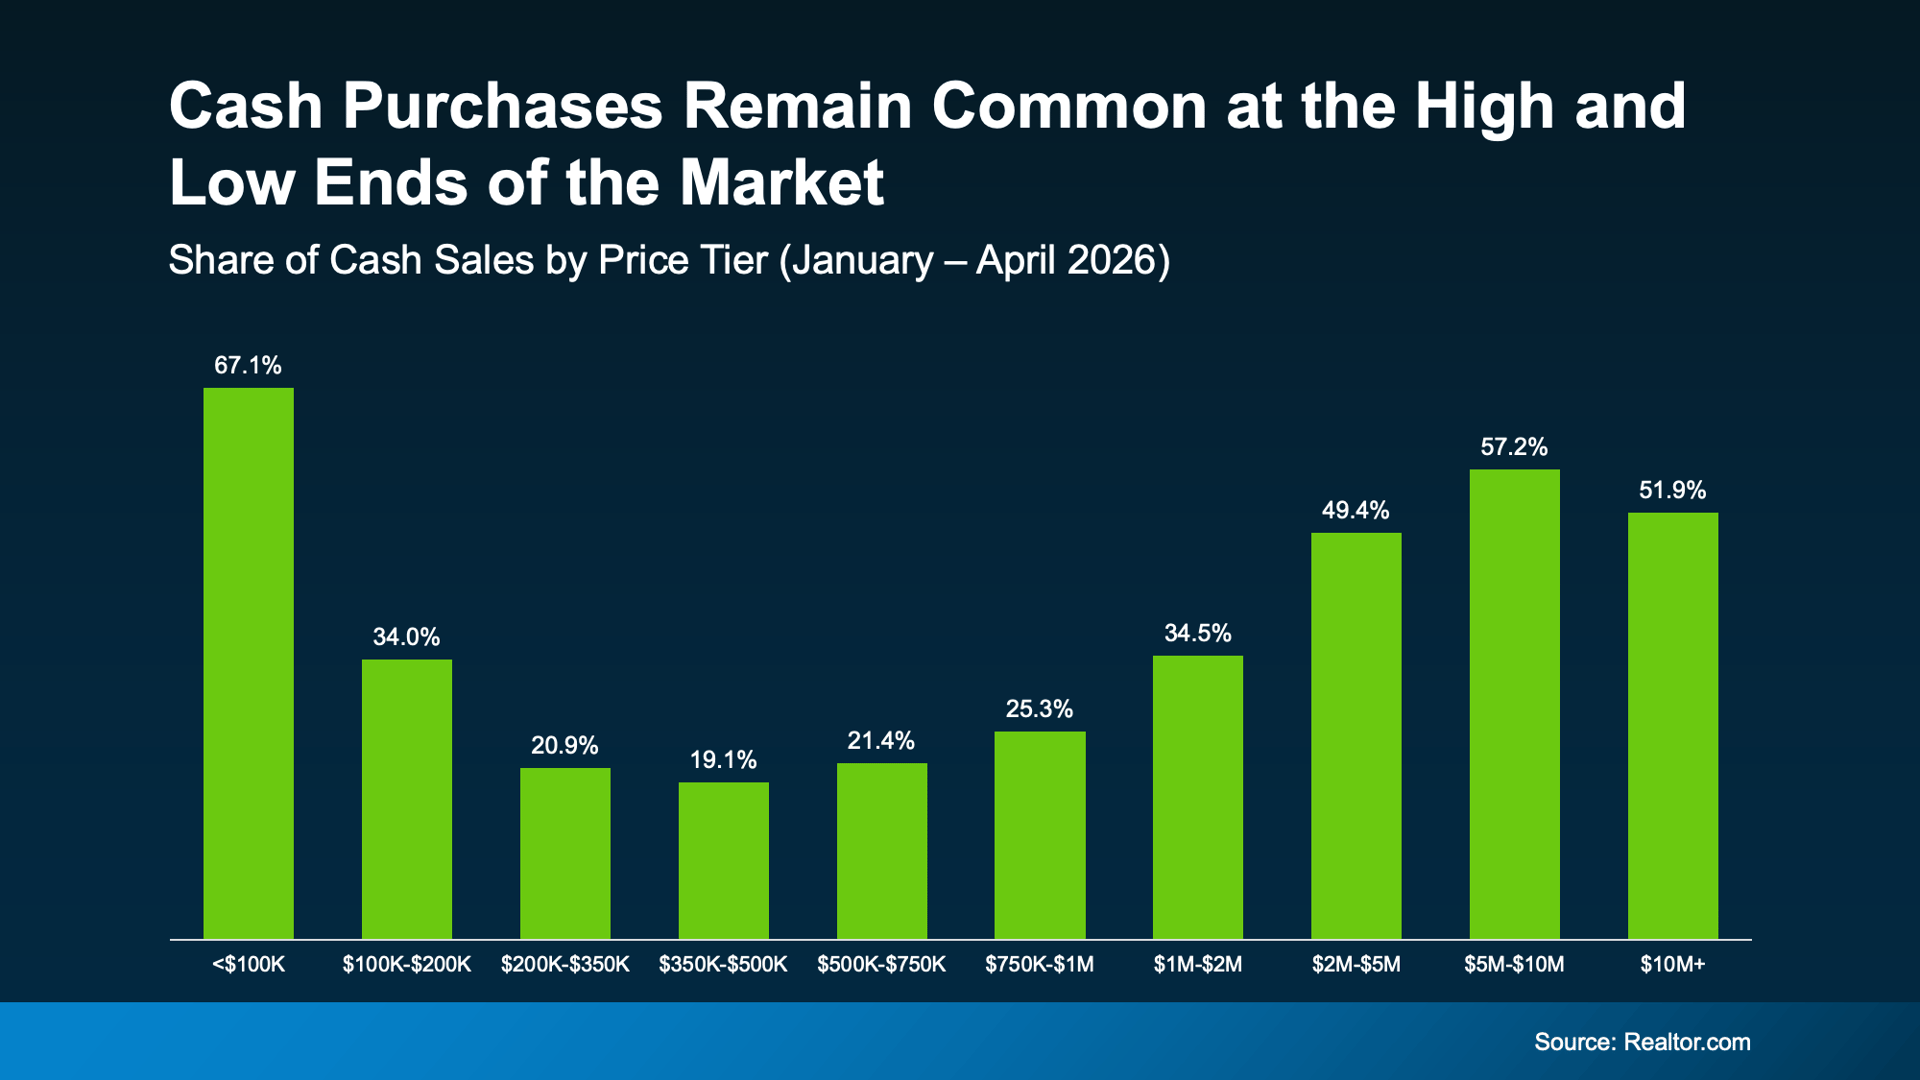
Data from Realtor.com shows that cash purchases are most common at the very highest and lowest price points in the market (see graph below):
For Buyers: If you have the ability to purchase with cash, an offer without a financing contingency can be especially attractive to sellers. It could help you close faster and may give you additional leverage when negotiating the terms.
For Sellers: Cash offers can reduce the risk of financing issues causing a deal to fall apart, but that added certainty may sometimes come with a lower purchase price. Before accepting, look at the full offer and weigh all of the terms rather than assuming the highest level of certainty is automatically the best fit.
Buyers Using Financing: They’re Not Getting Help from Rates, But They Are from Sellers
If you're planning to finance your next home with a mortgage, it's important to know that mortgage rates may not fall significantly anytime soon. In fact, data from Fannie Mae shows that nearly half of the experts surveyed have raised their long-term rate forecasts this year (see graphs below):
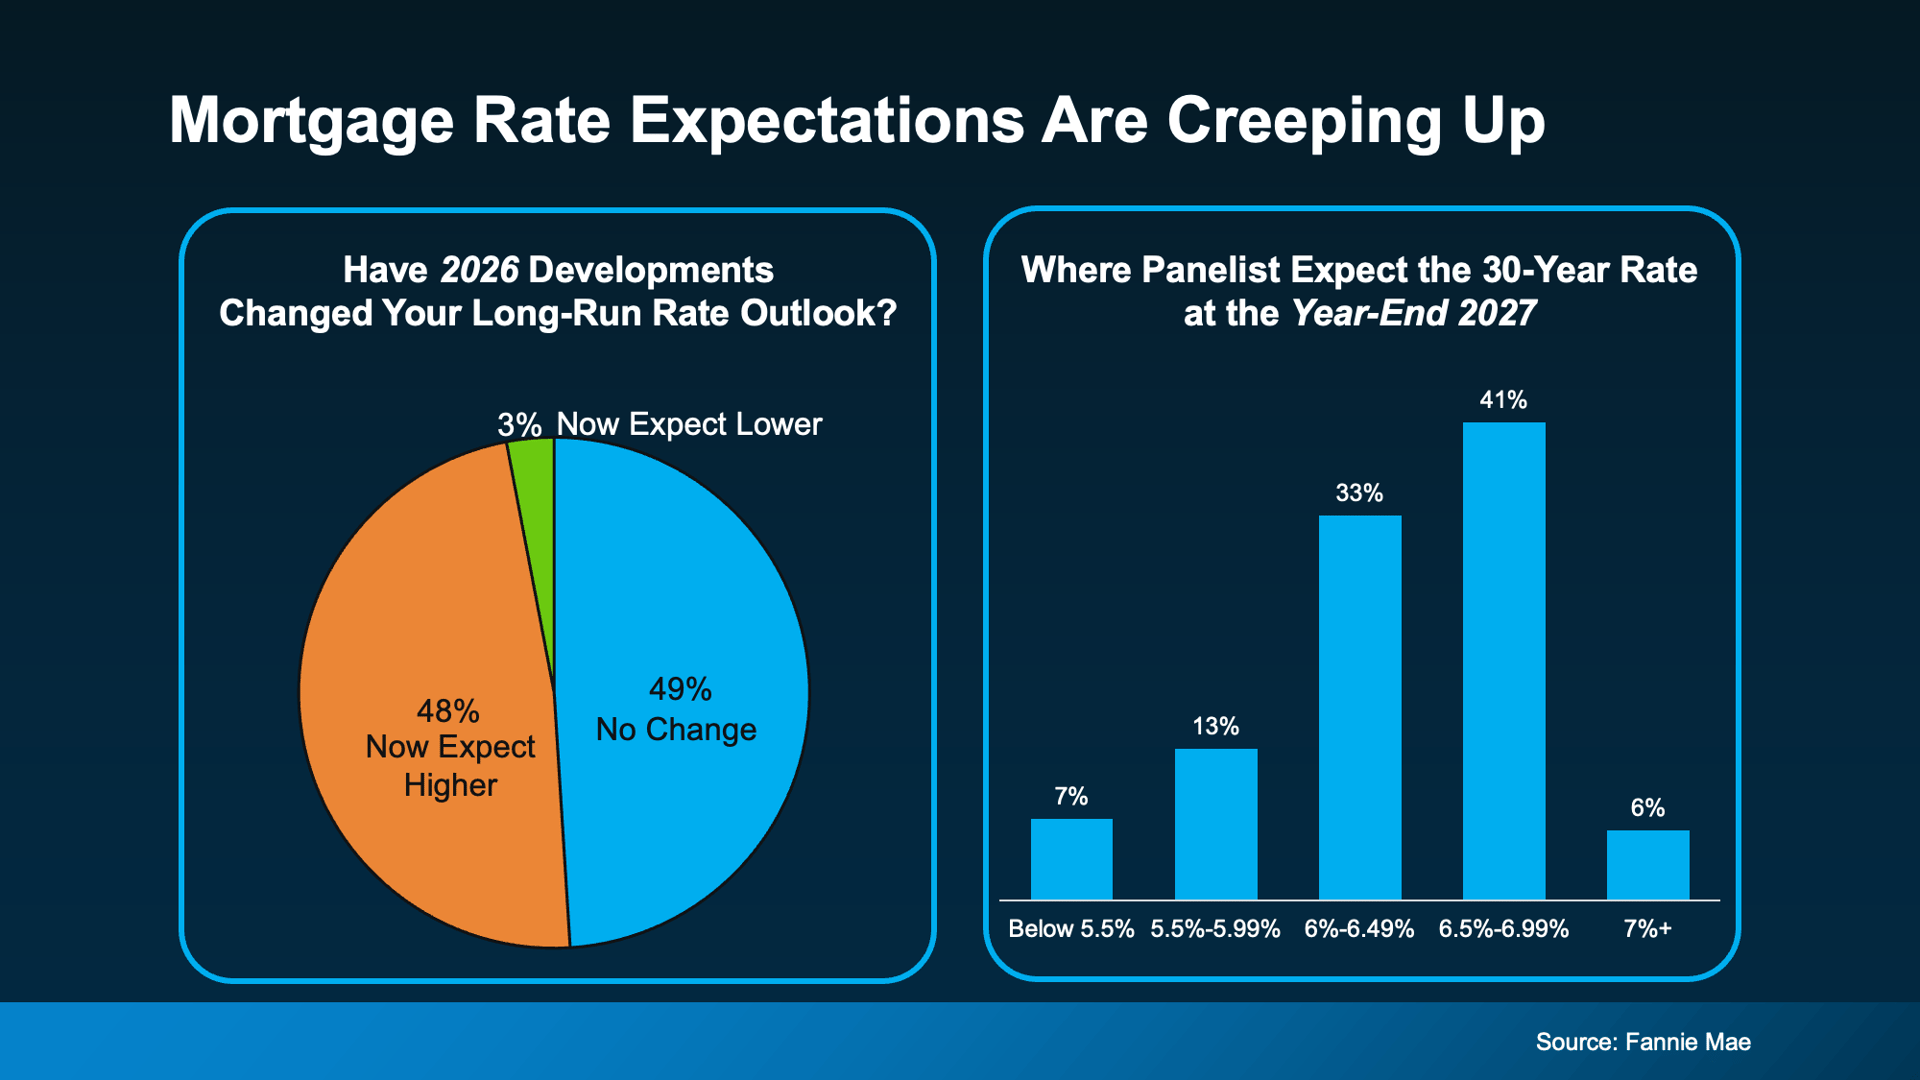
Higher rates can be especially challenging for buyers who need financing, particularly those purchasing their first home. But there is a potential upside.
Even if buyers aren't getting the lower mortgage rates they're hoping for, they may be able to negotiate with sellers for concessions that help make the purchase more affordable. According to Redfin data, nearly half of May home sales included a concession from the seller, such as a rate buydown or credit toward closing costs.
For Buyers: Don't make your entire strategy depend on waiting for rates to fall. Instead, consider negotiating for seller concessions that can reduce your upfront or monthly costs. If the numbers work for you today, that could be worth exploring.
For Sellers: Be prepared for negotiations. Factoring potential concessions into your pricing strategy from the beginning could help you attract buyers and get the transaction across the finish line.
Rate-Locked Homeowners: Most Are Sitting on a Rate Below 5%
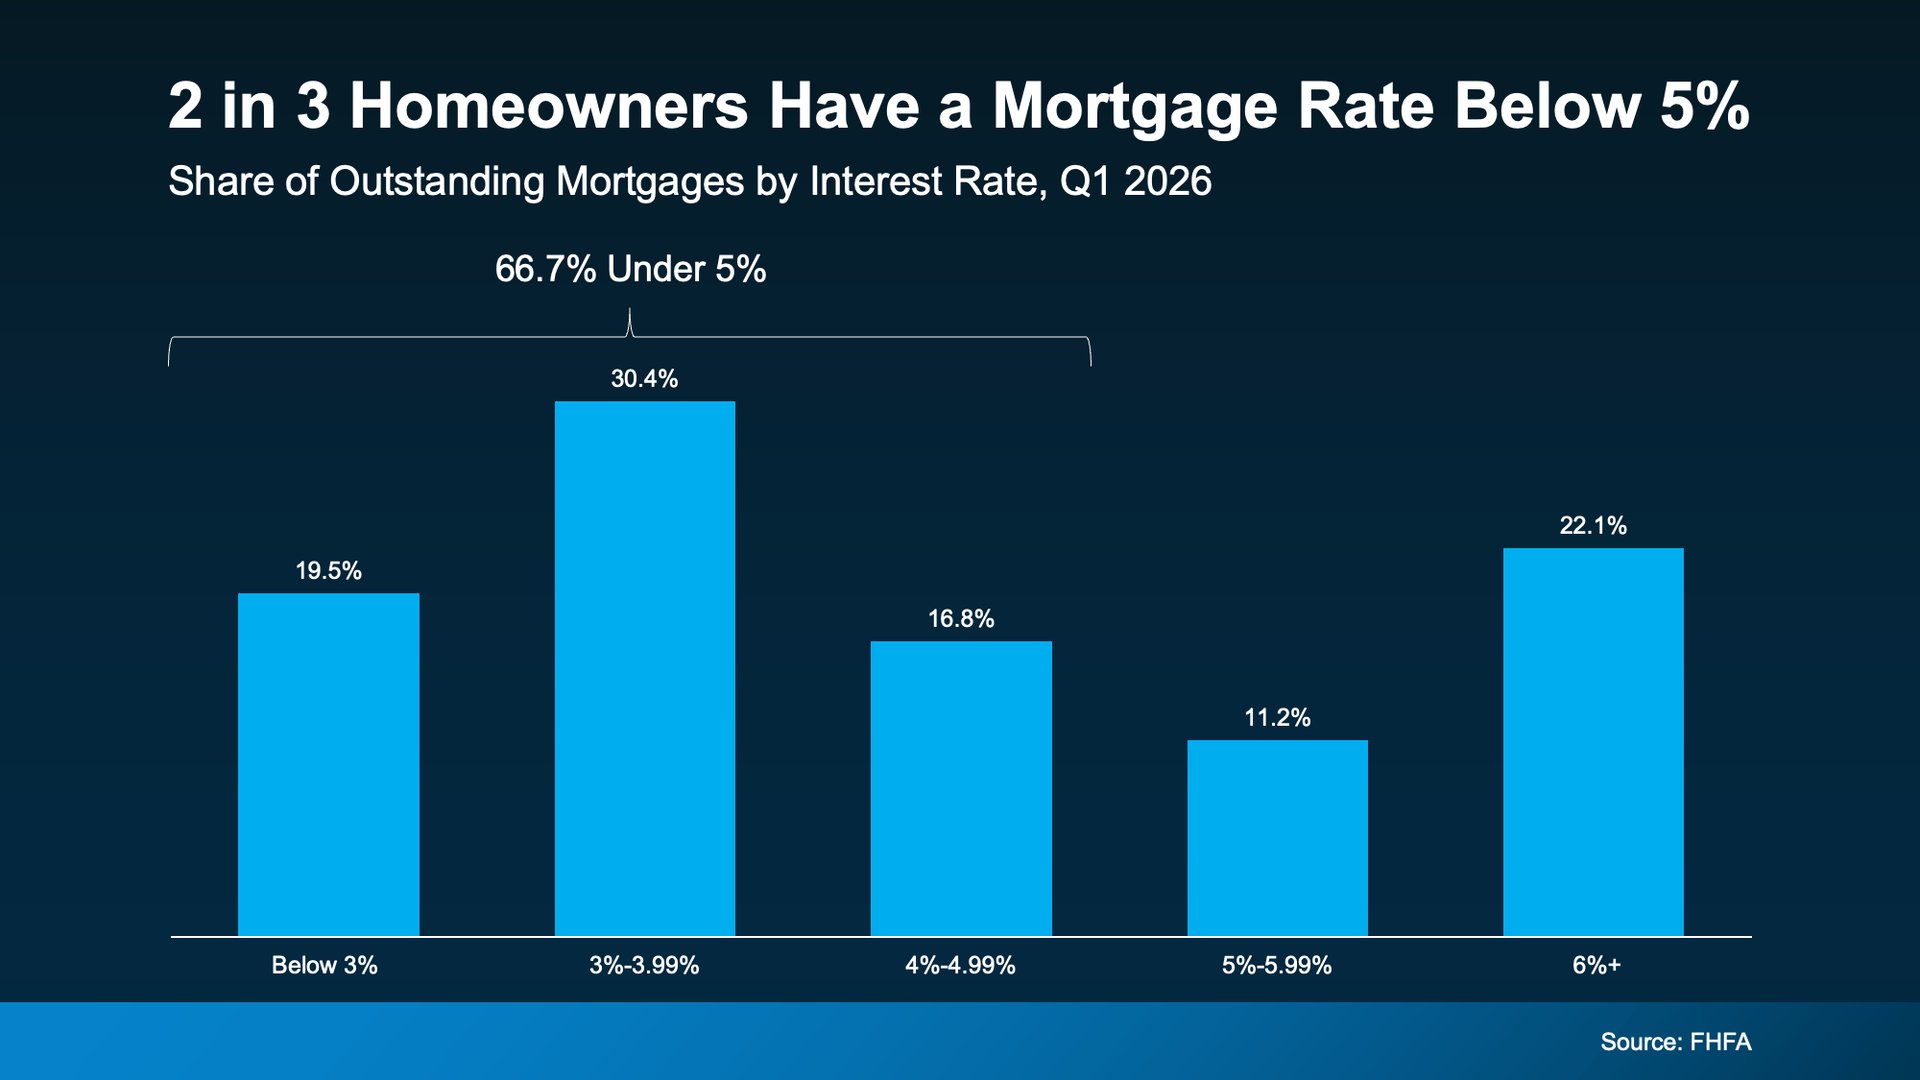
If you already own a home, you may be reluctant to move if doing so means giving up the low mortgage rate you currently have. And you're not alone. According to Federal Housing Finance Agency (FHFA) data, about 2 in 3 homeowners have a mortgage rate below 5% (see graph below).
When your current rate is that low, moving can be a difficult decision. Buying another home would likely mean taking on a higher mortgage rate, which makes it harder to justify giving up the one you have. That's where the term “rate locked” comes from, homeowners can feel stuck in place because their existing mortgage rate is so much more attractive than today's rates.
According to Fannie Mae data, most experts expect this rate lock-in effect to remain for another 3 to 5 years. That means it will likely continue influencing how many homeowners decide to put their properties on the market.
For Buyers: With fewer homeowners choosing to sell, those who do list are often moving because they have a specific reason to do so. That can mean you're more likely to encounter sellers who are motivated and willing to be flexible.
For Sellers: Before deciding that moving isn't financially realistic, take a close look at what your current equity could actually help you purchase. If you have an FHA or VA loan, ask whether your mortgage can be made assumable. It isn't common, but when available, it can give your home an additional selling advantage.
Homebuilders: They’re Negotiating More Than You Think
If you're considering a newly built home, current conditions could create some interesting opportunities. The latest Census data shows builders are carrying more unsold new homes than usual. At the current sales pace, it would take nearly 10 months to work through that supply, well above the typical 4 to 6 months. As a result, builders are increasingly offering price reductions and mortgage rate buydowns to attract buyers.
For Buyers: This is where some of the strongest opportunities may be found. Just make sure you have your own agent representing you, and look at the builder's complete incentive package rather than focusing only on the list price.
For Sellers: Highlight the advantages a new construction home can't provide, such as mature landscaping, an established neighborhood, and a home that's available now instead of requiring an 8-month wait. Those features can help your property stand out against new construction.
Bottom Line
Today's housing market is really four different markets happening at the same time: cash buyers, financed buyers, homeowners who are rate locked, and builders. Each group is navigating a different set of conditions, so a strategy that works for one may not make sense for another.
Whether you're planning to buy or sell, don't let a one-size-fits-all approach determine your next move. Reach out to us today to discuss your options, understand what's happening in our local market, and create a strategy tailored to your goals.