When it comes to the housing market, two important questions are top of mind for many buyers and sellers right now:
- What can we expect from mortgage rates?
- How are home prices likely to change moving forward?
If you're trying to decide whether to make a move in the coming months or hold off until 2027, here's what you need to understand.
Looking ahead, housing experts are forecasting a relatively stable market in 2027. Rather than dramatic ups and downs or major unexpected changes, they're anticipating a more balanced and predictable environment.
And that kind of stability can make it much easier to plan your next move. Let's take a closer look.
Rates Are Expected To Settle into a Steady Range
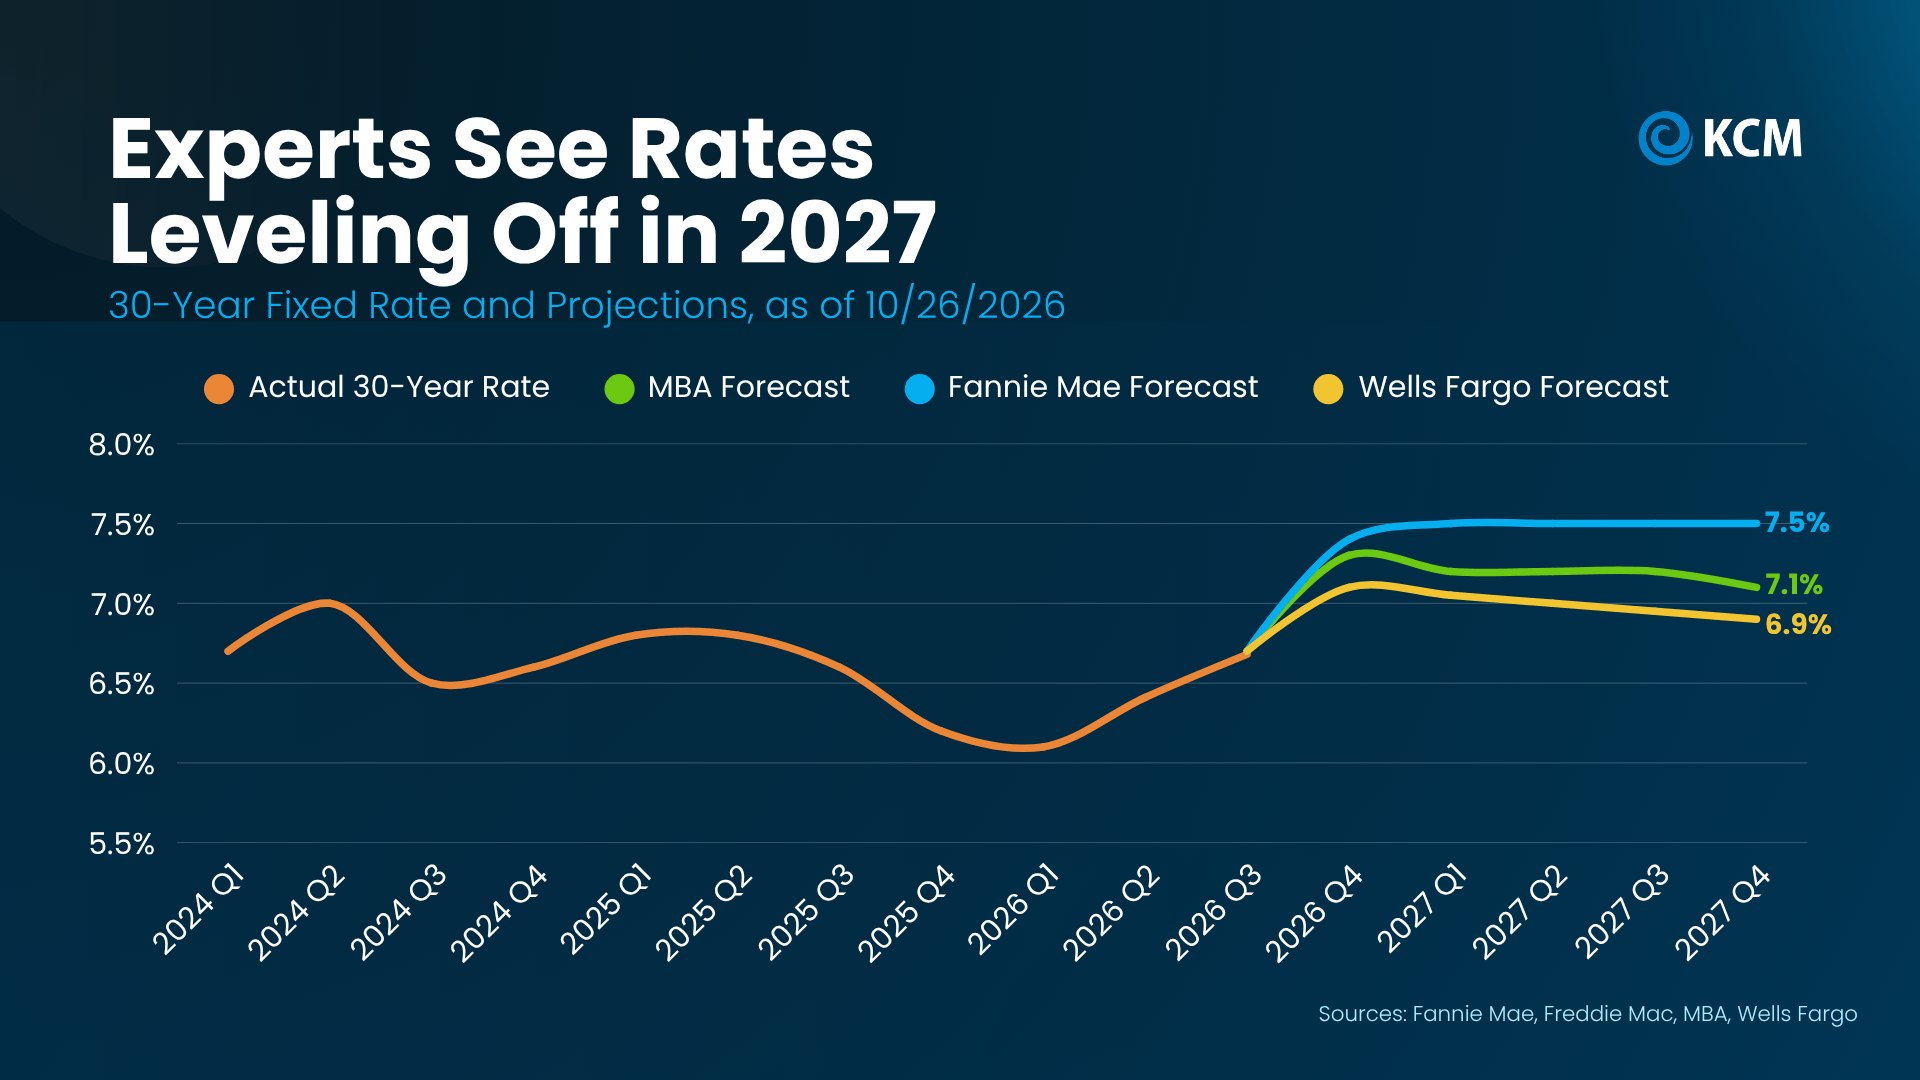
Many buyers are hoping mortgage rates will come down before making their next move. However, the latest projections from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo suggest mortgage rates will remain relatively steady through 2027, rather than experience any major declines (see graph below):
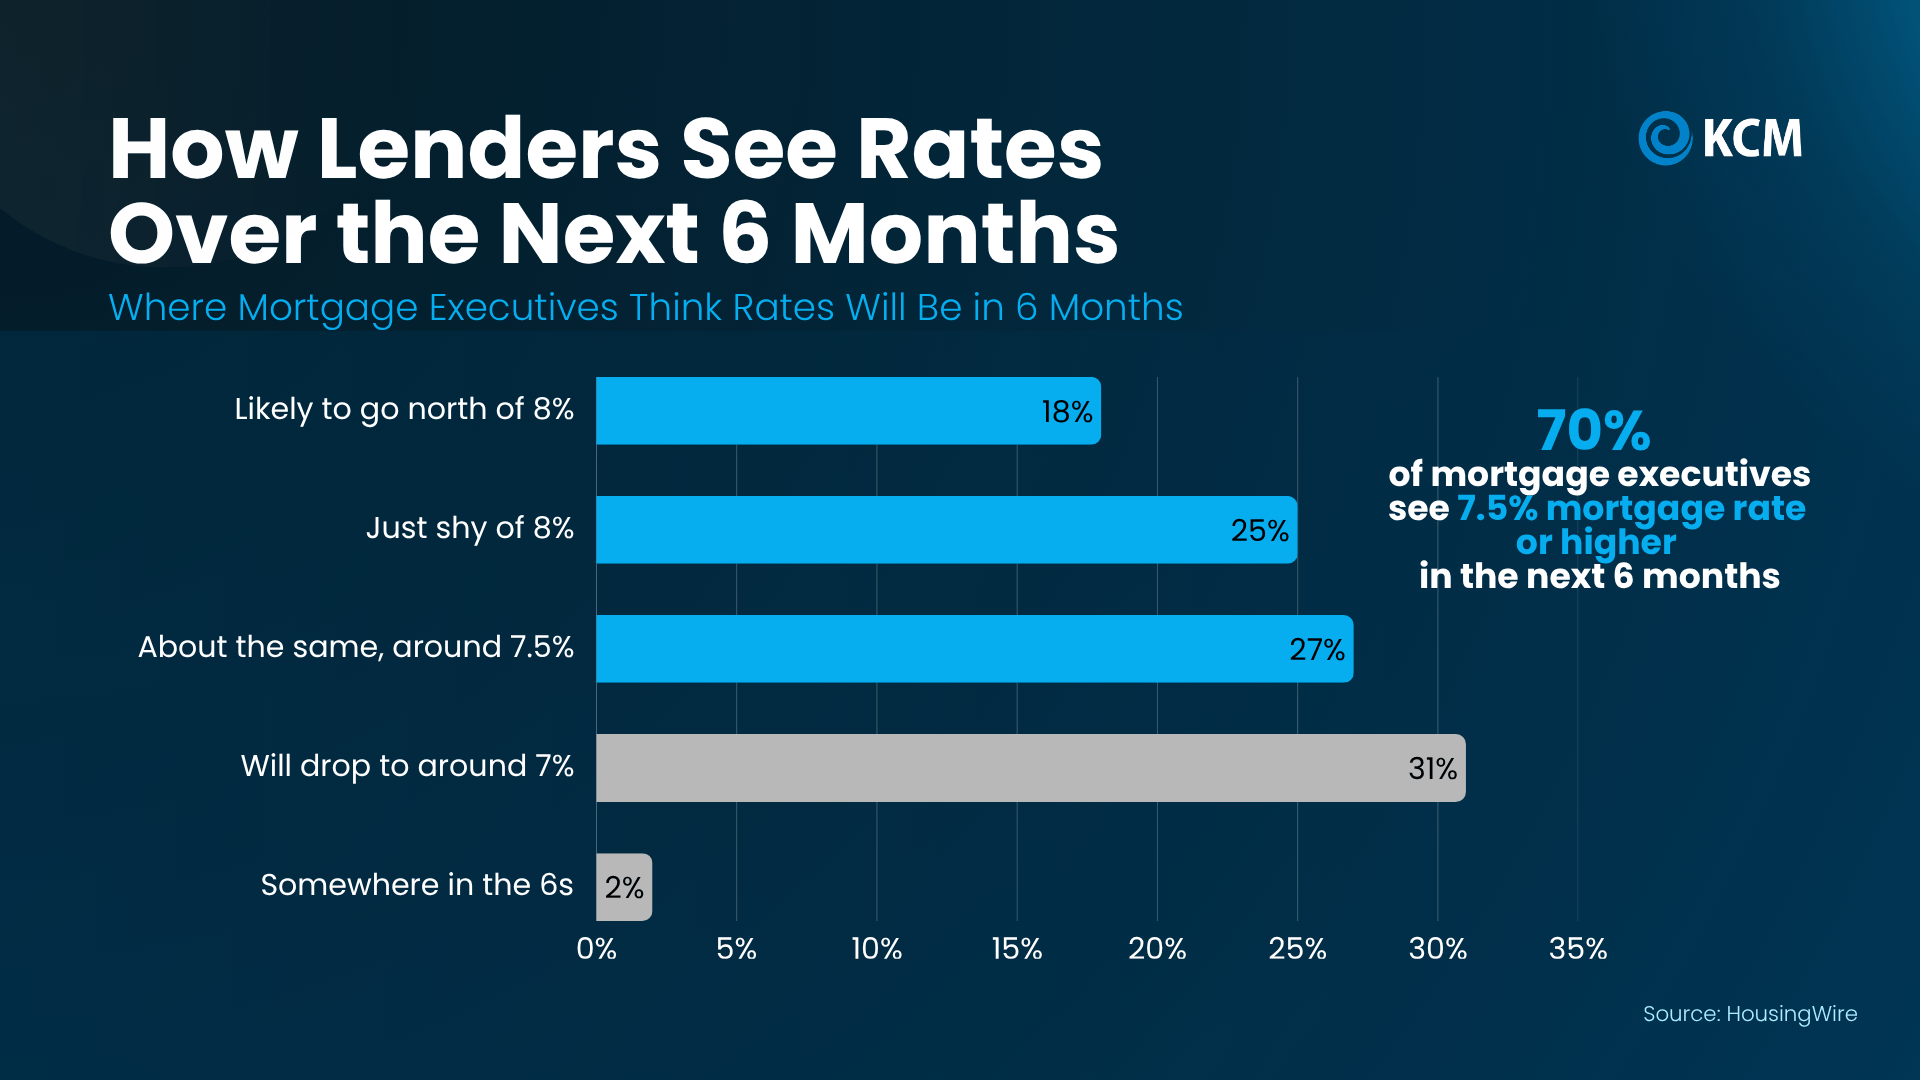
Mortgage industry leaders are sharing a similar outlook. In a recent HousingWire survey, 70% of mortgage executives said they expect rates to remain at approximately 7.5% or higher over the next six months (see graph below):
If you're wondering what's keeping mortgage rates elevated, the explanation comes down to broader economic conditions. As Chen Zhao, Head of Economics Research at Redfin, explains:
Until the underlying economic fundamentals, everything from oil prices to AI, that are keeping rates high change, mortgage rates are unlikely to fall significantly.
What does this mean if you're planning to buy a home? Rather than trying to predict the next rate movement, it's more productive to focus on the factors within your control. Even if mortgage rates remain where they are, you may still have opportunities to secure a better rate. When speaking with your lender, be sure to ask about:
- Your credit score. Improving your credit score, even by a few points, could help you qualify for a lower mortgage rate.
- Different loan options. Certain loan programs may offer more competitive rates or lower down payment requirements than you realize.
- Buying down your rate. Paying additional upfront costs, known as discount points, may help reduce your interest rate and monthly mortgage payment.
Having these conversations with your lender can give you a clearer picture of your financing options and help you determine what monthly payment comfortably fits your budget.
Prices Should Keep Climbing, Just More Slowly
What about home prices? This is another area where a stable market can work to your advantage.
Housing experts aren't predicting a decline in home values. Instead, the average projections from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo point to modest annual price growth of approximately 1% to 1.5% through 2027 (see graph below):
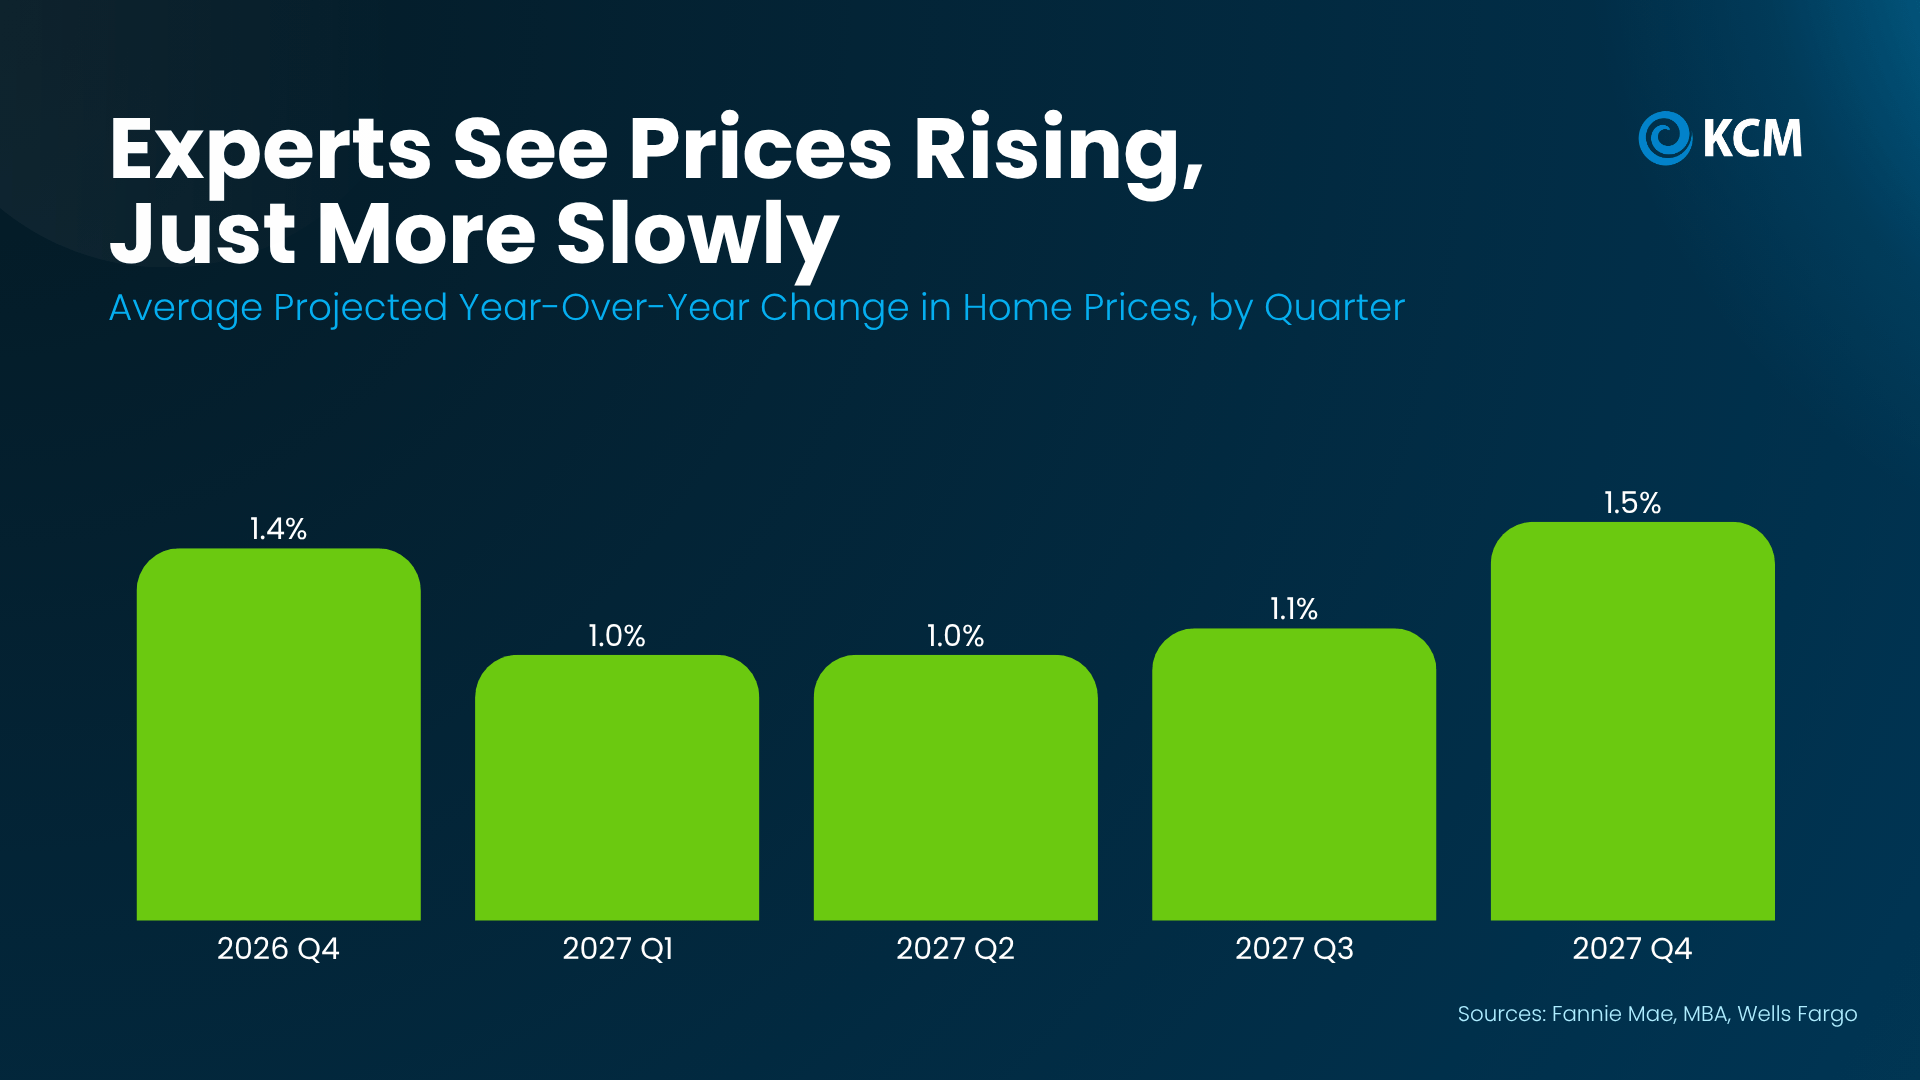
Put simply, home prices are expected to keep increasing in most markets, but at a more moderate pace. For sellers, this suggests that home values should remain relatively stable. For buyers, slower appreciation may provide a bit more time and flexibility when making a decision. However, waiting for prices to drop significantly may not be the best strategy.
It's also important to remember that these projections reflect national trends. Real estate conditions can vary considerably between markets, so the most useful insight will come from understanding what's happening in your local area.
The Best Time To Move Is When It Fits Your Life
In a more stable housing market, there's less pressure to wait for the perfect moment to make a move. Without major market swings, you can focus more on your own plans instead of trying to predict what prices or mortgage rates will do next.
Ultimately, your decision should come down to what makes sense for your life. Maybe you need additional space as your family grows, or perhaps you're ready to downsize and enjoy a home that requires less maintenance. A steady market can make it easier to plan for either transition with greater confidence.
Bottom Line
If you're trying to decide whether to move now or wait until 2027, keep in mind that experts are expecting a relatively stable housing market, with mortgage rates staying close to current levels and home prices continuing to rise gradually.
Instead of putting your plans on hold while waiting for a major market change that may never happen, let's look at what buying or selling could mean for you under today's market conditions. Reach out to Holly & Chris, and we'll help you review your options, understand what's happening in your local market, and develop a strategy that aligns with your budget, priorities, and long-term goals.